Types of Care
In-Home Care for Seniors: Services and Who Pays
What Is In-Home Care for Older Adults, and Who Pays for It?
In home care for elderly parents and spouses is help delivered where they live: personal care like bathing and dressing, household chores, meals, rides and, when a doctor orders it, skilled nursing or therapy. Medicare pays only for part-time skilled home health care for people who are homebound, not for ongoing personal care. Most families pay privately or through a state Medicaid waiver, the VA or long-term care insurance.
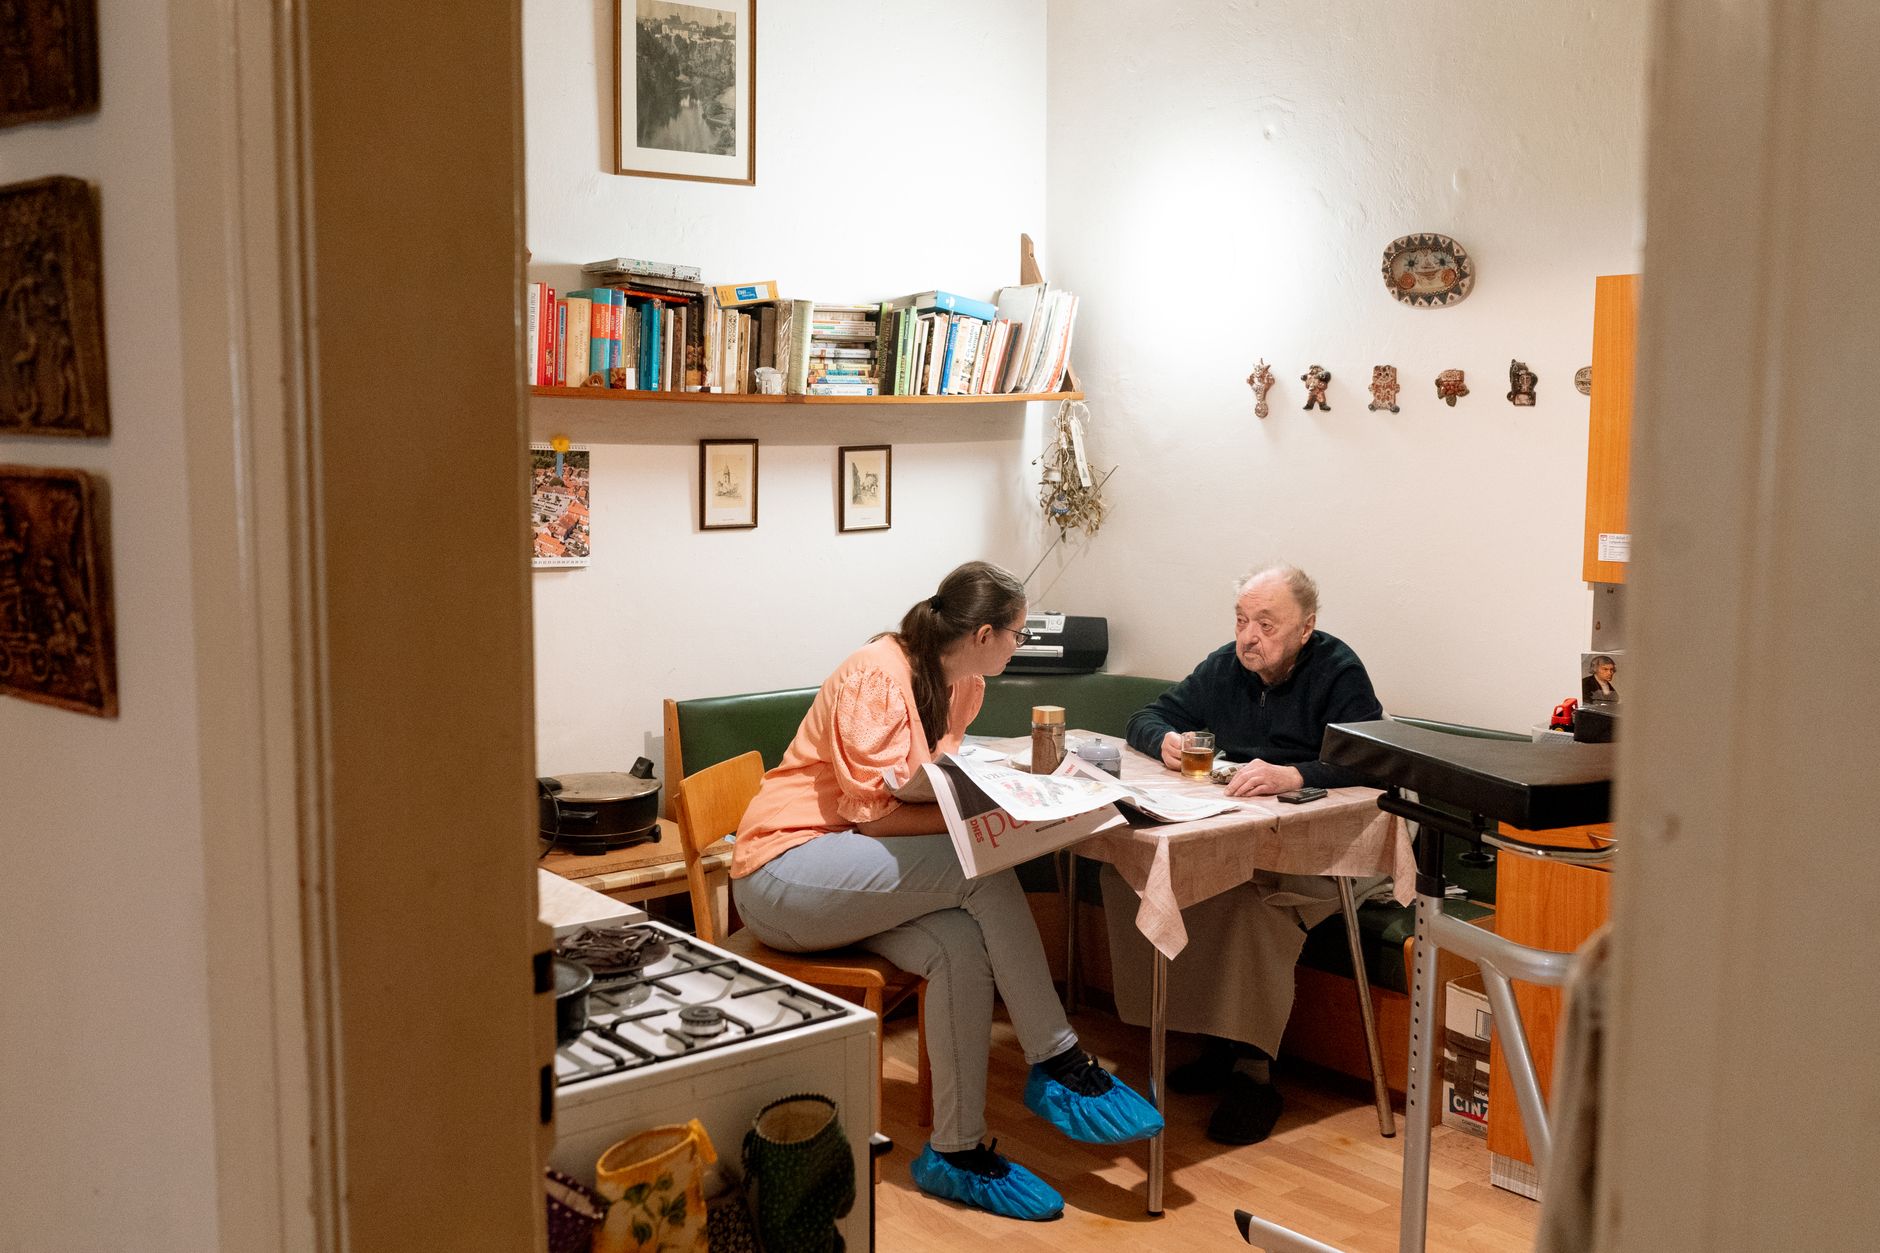
In-home care lets your parent stay in a familiar place while someone else takes on part of the work of daily living. It can be a few hours of help a week with showers and groceries, or a nurse visiting after a hospital stay to dress a wound. Most families end up using a mix of family help, paid aides and community services.
The hard part is the bill. Medicare covers far less home care than most people expect, and the programs that do pay for ongoing help are run state by state. This guide explains what in-home care includes, what each payer covers, and how to set it up.
What In-Home Care for Elderly Parents Includes
The National Institute on Aging groups help at home into a few kinds. Personal care is help with the everyday tasks called activities of daily living: bathing, dressing, grooming, using the toilet, eating and moving around, such as getting out of bed and into a chair. Household help covers cleaning, laundry, yard work and grocery shopping. Other services include preparing meals, paying bills, rides to the doctor and safety features such as a medical alert system.
Then there is health care at home: giving medications, caring for wounds, helping with medical equipment and physical therapy. NIA notes that in-home services can be short-term, for someone recovering from an operation, or long-term, for someone who needs ongoing help.
Two words cause most of the confusion:
- Home care usually means non-medical help: personal care, companionship and chores, from aides or homemakers.
- Home health care means skilled care a doctor orders: nursing, physical or occupational therapy, speech therapy. This is the part Medicare can pay for.
The home health vs home care guide goes deeper on that split. If your parent needs both, one agency may provide both, or you may use two.
Who Provides the Care
Family does most of it. ACL’s LongTermCare.gov says most long-term care is provided at home, often by unpaid family members or friends, with paid help filling in. That paid help usually comes from one of three places:
- A home care agency that employs, screens and schedules aides and homemakers, and sends a substitute when an aide is sick.
- A Medicare-certified home health agency, which provides nurses, therapists and aides under a doctor’s plan of care.
- A worker you hire directly, either privately or through a Medicaid self-directed program.
VA describes a homemaker or home health aide as a trained person who helps with eating, grooming, bathing, dressing, using the bathroom, moving around and grocery shopping. They are not nurses, and in VA’s program a registered nurse supervises them.
If you live far from your parent, NIA suggests a geriatric care manager, a professional who assesses needs, builds a care plan and lines up services. Your parent’s doctor or the local Area Agency on Aging can point you to one.
Does Medicare Pay for In-Home Care?
Only for skilled, part-time care, and only for people who are homebound. Medicare.gov sets out the conditions: leaving home isn’t recommended because of your parent’s condition, or leaving takes a major effort, and your parent needs part-time or intermittent skilled nursing or therapy. A doctor or other allowed provider must certify this and set up a plan of care with a Medicare-certified home health agency.
When those conditions are met, your parent pays nothing for covered home health services. Medical equipment such as a walker is separate: after the Part B deductible, your parent pays 20% of the Medicare-approved amount.
Medicare’s home health booklet adds a useful detail: home health aide help with bathing or dressing is covered only while your parent is also getting skilled care. And “part-time” has a limit, generally up to 8 hours a day combined and no more than 28 hours a week, with up to 35 hours allowed for a short time when needed.
What Medicare doesn’t pay for at home:
- 24-hour-a-day care;
- meal delivery;
- homemaker services such as shopping and cleaning that aren’t part of the care plan;
- personal care, like bathing and dressing, when that is the only care your parent needs.
That last item is the one that matters for most families. A parent who needs help showering every morning but no nursing or therapy gets no Medicare home care at all. Medicare.gov is direct about it: Medicare doesn’t pay for long-term care, and you pay all costs for it unless another program steps in. The Medicare and nursing homes guide explains the same rule for facility care.
Who Pays for Ongoing In-Home Care
| Payer | What it can cover at home | Main conditions |
|---|---|---|
| Medicare | Part-time skilled nursing, therapy, aide help during skilled care, medical social services | Homebound, doctor’s plan of care, Medicare-certified agency |
| Medicaid | Personal care, homemaker help, adult day, respite and more through state waivers and state plan options | Income and asset limits and a level of need set by the state |
| VA | Homemaker and home health aide care; Aid and Attendance cash added to a VA pension | Enrolled Veteran meeting clinical criteria; pension rules for Aid and Attendance |
| Long-term care insurance | Home care, depending on the policy | The policy’s benefit triggers and waiting period |
| PACE | Medical and social services, including adult day center care | Age 55+, lives in a PACE service area, needs a nursing home level of care |
| Your family | Anything you arrange | Your savings and income |
Medicaid Waivers and Home Care Programs
For ongoing personal care at home, Medicaid is the public program to check first. Medicaid.gov says home and community-based services (HCBS) let people get care in their own homes or communities rather than institutions, and that 63.2 percent of Medicaid long-term services spending went to HCBS in 2021. States have several tools: section 1915(c) waivers, which 47 states and DC operate, plus state plan options such as 1915(i), 1915(j) and 1915(k) Community First Choice.
Each state names its programs differently. A few examples from state pages:
- Ohio: PASSPORT, covered on the Ohio page.
- Massachusetts: the Frail Elder Waiver, on the Massachusetts page.
- Michigan: the MI Choice Waiver Program, on the Michigan page.
- Texas: STAR+PLUS home and community-based services, on the Texas page.
- Connecticut: the Connecticut Home Care Program for Elders, on the Connecticut page.
- Missouri: besides its Aged and Disabled Waiver, Missouri runs a Structured Family Caregiving Waiver, listed on the Missouri page.
The Medicaid waivers guide explains how waivers work, and the Medicaid long-term care checker shows the 2026 income and asset rules for your parent’s state.
Can Family Caregivers Be Paid?
Sometimes. Medicaid.gov describes self-directed services, where the person getting care, or a representative, can recruit, hire, train and supervise their own workers. ACL says those workers can include family and friends. Each state sets its own rules on which relatives can be paid, so ask the state Medicaid agency before you count on it.
VA Help at Home
VA offers homemaker and home health aide care to enrolled Veterans who meet clinical criteria and are eligible for community care, with a possible copay based on disability status. Separately, VA Aid and Attendance adds a monthly payment to a VA pension for Veterans and survivors who need help with daily activities like bathing, feeding and dressing. Families often use that money toward home care. The VA long-term care guide covers both.
Insurance and Private Pay
A long-term care insurance policy may cover home care once its benefit triggers are met. Read the policy’s home care section and call the insurer before hiring, so you know which caregivers it will pay for. Without insurance or Medicaid, families pay from income and savings. NIA lists other private sources, including reverse mortgages, certain life insurance policies and annuities.
How to Set Up In-Home Care
- Write down what help is needed and when. Note mornings, evenings, nights and weekends. The hours drive the cost and the kind of help.
- Ask the doctor whether skilled care is needed. If your parent is homebound and needs nursing or therapy, Medicare home health may cover part of the plan.
- Call the Area Agency on Aging. The Eldercare Locator, 1-800-677-1116, connects you to it. It can screen for Medicaid waivers, Older Americans Act services and meals.
- Apply for Medicaid early if your parent might qualify. Approval takes paperwork and a needs assessment, so start before a crisis.
- Compare agencies. For Medicare home health, use Medicare’s Care Compare and ask the State Survey Agency for the agency’s inspection report.
- Set a backup plan. Know who covers a missed shift.
The Care Options Guide can help you sort out whether home care, adult day care or a residential setting fits your parent’s needs today.
Questions to Ask a Home Care Agency
| Ask | Why it matters |
|---|---|
| Is the agency licensed by the state, and is it Medicare-certified? | Only a Medicare-certified agency can bill Medicare for home health. |
| Are aides employees, and are they screened and trained? | It tells you who supervises them and who handles payroll. |
| Who supervises aides, and how often does a nurse visit? | VA’s own model has a registered nurse supervising aides. |
| What happens when an aide calls in sick? | Missed shifts are a common failure point. |
| Is there a minimum number of hours per visit or per week? | It tells you whether a short daily check-in is possible. |
| Which payers does the agency accept? | Medicaid waivers, VA and insurance each work with specific agencies. |
| How do I raise a concern or change aides? | You want a named contact and a clear process. |
Safety and When Home Care Isn’t Enough
Home care works best when your parent is safe between visits. ACL suggests home changes such as grab bars, better lighting, handrails and a medical alert system. If your parent is 60 or older, ACL says to ask the local Area Agency on Aging about home modification and repair funds from the Older Americans Act.
If you suspect an aide is mistreating or neglecting your parent, call 911 if anyone is in immediate danger. Otherwise, report it to Adult Protective Services in your parent’s state; the Justice Department’s elder abuse page links to every state’s APS office, and the Eldercare Locator can help too. The abuse warning signs guide explains how reporting works.
There may come a point when your parent needs more supervision than visits can give, especially overnight. Medicare doesn’t pay for 24-hour care at home. That is often when families look at assisted living or a nursing home. The nursing home finder shows CMS ratings for every certified home near your parent. CMS rates 2,981 nursing homes 5 stars overall (data from August 2026).
Frequently Asked Questions
Can a Family Member Get Paid to Provide In-Home Care?
In some states, yes. Medicaid lets states offer self-directed services, where the person getting care, or a representative, can recruit, hire and supervise their own workers. ACL's LongTermCare.gov says those workers can include family and friends. Whether a spouse or adult child can be paid depends on your state's program rules, so ask the state Medicaid agency or your Area Agency on Aging.
Does Medicare Pay for a Home Health Aide to Help With Bathing?
Only alongside skilled care. Medicare covers part-time home health aide services, like help bathing, when your parent is homebound and also getting skilled nursing or therapy under a doctor's plan of care. If bathing and dressing help is the only care needed, Medicare doesn't pay for it.
Is In-Home Care Less Expensive Than a Nursing Home?
It can be. The National Institute on Aging says home-based services can be expensive but may cost less than moving into assisted living or a nursing home. The answer turns on hours: a few visits a week is a very different bill from round-the-clock help, which Medicare never covers at home.
How Do I Find In-Home Care Services Near My Parent?
Call the Eldercare Locator at 1-800-677-1116 to reach the local Area Agency on Aging, which knows the home care, meal and transportation services in your parent's county. For skilled home health, use Medicare's Care Compare to find Medicare-certified agencies. Your parent's state page lists the Medicaid waiver that covers home care.
What Is the Difference Between a Homemaker and a Home Health Aide?
A homemaker helps with the house: cleaning, laundry, shopping and meals. A home health aide helps with the person: bathing, dressing, using the bathroom and moving around. VA describes its homemaker and home health aide workers as trained, but not nurses, and supervised by a registered nurse.
Can In-Home Care Work for a Person Living With Dementia?
Often, for a time. Aides can provide supervision, help with daily routines and give the family caregiver breaks. As needs grow, many families add adult day care or respite stays. The dementia care options guide walks through each setting and when families usually move to the next one.
More on Types of Care
- Memory CareSecured dementia care in assisted living and nursing homes, state rules and how to pay
- Assisted Living vs Nursing HomeHow the two settings differ in care, rules and who pays
- Memory Care vs Assisted LivingWhen a person with dementia needs a secured memory care unit
- Home Health vs Home CareThe difference between Medicare home health and paid personal care
- Adult Day CareDaytime programs, health services and coverage
- Respite CareIn-home, adult day and short-stay respite and who pays
This guide explains long-term care in plain language from official sources. It isn't medical, legal or financial advice; a doctor, your state Medicaid agency or an elder law attorney can advise on your situation.
Sources
- Medicare.gov: Home health services
- Medicare.gov: Long-term care
- Medicare & Home Health Care (CMS Product No. 10969)
- National Institute on Aging: Aging in Place, Growing Older at Home
- Medicaid.gov: Home and Community Based Services
- Medicaid.gov: HCBS authorities
- Medicaid.gov: Self-directed services
- VA: Homemaker and Home Health Aide Care
- VA: Aid and Attendance and Housebound benefits
- LongTermCare.gov (ACL): Where can you receive care?
- Justice Department: Find help or report abuse
- LongTermCare.gov (ACL): Staying in your home
- Medicare.gov: PACE